Uncertain carbon credit revenues in agriculture are making it difficult to assess how much projects can earn beyond their core business activities.
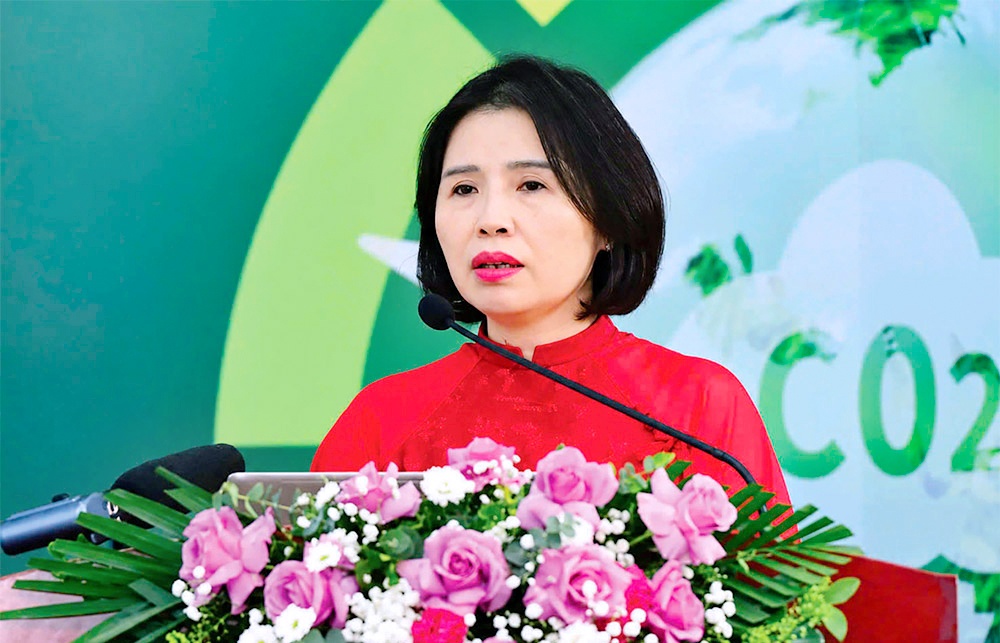
Nguyen Thi Thu Ha, deputy head of Agribank’s Steering Committee for Environmental, Social, and Governance
Nguyen Thi Thu Ha, deputy head of Agribank’s Steering Committee for Environmental, Social, and Governance, highlighted these constraints and more at VIR’s seminar on credit policy and the carbon market last week in Hanoi. She said financing arrangements needed to reflect project viability, repayment capacity, and the timing of expected returns.
“Carbon credit revenue can supplement project returns, but it cannot be treated as a reliable source of repayment before the conditions for generating and selling those credits are established,” said Ha.
Vietnam’s shift towards lower-emission production is creating funding needs beyond equipment and technology. Businesses must also pay for project preparation, environmental monitoring, and changes to production processes, while ensuring that investments generate sufficient returns to service debt.
“The domestic carbon market remains at an early stage, making the commercial contribution of carbon credits dependent on project readiness and market development,” she added.
Vietnam has continued to develop the regulatory framework for emissions reduction and carbon market activities, including plans for a domestic carbon exchange and rules governing international carbon credit transactions. Greenhouse gas inventory requirements have also expanded. The number of covered facilities rose from 1,912 in 2022 to 2,441 in September 2026. Criteria have also been expanded for identifying green projects, including circular economy activities.
However, meeting environmental requirements does not in itself make a project commercially viable or eligible for bank financing. Businesses may still need feasibility studies, technical assessments, environmental monitoring systems, and agreements covering production, purchasing, and the distribution of financial benefits.
In agriculture and rural development, low-emission rice cultivation, livestock waste treatment, sustainable forestry, and biomass utilisation require funding at different stages of the value chain. Financing must account for the needs of farmers, cooperatives, and processors, as well as seasonal production cycles, market access and operating costs.
Across the value chain
Green projects require funding at several stages, from feasibility studies and environmental assessments to equipment, working capital, monitoring, and compliance. For small producers, the cost of preparing a project can be a barrier before any return is generated. Once operations begin, maintenance and verification add to expenditure, while purchasing and processing businesses need capital to handle agricultural output.
For that reason, Ha emphasised the need to align financing with project costs and cash flow cycles. In agriculture, adopting new cultivation methods can increase expenses before additional income materialises, while seasonal production and delays between delivery and payment can put pressure on borrowers’ liquidity.
“Financing arrangements need to reflect the costs incurred at each stage of a project, the timing of expected cash flows and the borrower’s repayment capacity,” Ha said.
Commercial loans can finance equipment and working capital where credible repayment sources exist, while technical assistance, concessional funding, and guarantees may help cover project preparation costs or address specific risks.
The source of repayment is particularly important for projects that expect to earn carbon credit revenue. Reduced energy and material consumption can lower operating costs directly, but income from carbon credits depends on project eligibility, verification, buyer demand, and payment terms.
“Businesses cannot treat carbon credit revenue in the same way as savings from reduced energy or material consumption. Income from credits depends on whether emissions reductions can be verified and the credits sold,” she added.
Agribank’s existing agricultural lending provides a channel for financing investment in lower-emission production, according to Ha. By mid-2026, the bank’s assets exceeded $108 billion, deposits surpassed $100 billion and outstanding loans topped $80 billion. At the end of August, lending to agriculture, farmers, and rural areas exceeded $53.6 billion, equivalent to 64.7 per cent of total outstanding loans.
She also outlined the bank’s reach among smaller borrowers. As of July 31, Agribank’s more than 58,000 lending groups comprised over 910,000 members, with total loans exceeding $8.64 billion.
“These established lending relationships could provide a route to identifying farmers and cooperatives seeking to invest in resource efficiency or emissions reduction. However, such projects would still need to meet the bank’s lending requirements, including those relating to project readiness and repayment capacity,” Ha shared.
Agribank’s green credit programmes provide further funding channels. Its green credit portfolio stood at nearly $1.2 billion at the end of March. For the year, the bank has allocated $120 million to a programme targeting individual customers and $2 billion to clean and high-tech agriculture. It also operates a programme worth at least $1.2 billion to support production, processing, and consumption under the Mekong Delta’s one-million-hectare project for high-quality, low-emission rice cultivation.
The rice initiative illustrates the need to coordinate financing across the agricultural supply chain. Farmers may require seasonal loans to adopt new cultivation methods, while cooperatives need equipment and working capital to coordinate production and collect data. Technical partners can provide training and support environmental measurement, while processors need funds to purchase and handle the crop.
“Financing needs to be considered across the value chain, from production and data collection to purchasing and processing,” Ha said.
Agreements covering production standards, data collection, purchasing volumes, and payment terms can clarify participants’ obligations and expected returns. Where preparation costs remain unaffordable, technical assistance or concessional funding could help cover the shortfall, allowing commercial loans to focus on investments with credible repayment sources.
Bankable projects
Bankable carbon projects depend on whether emissions reductions can generate reliable cash flow. In agriculture, this requires coordination between Agribank, technical specialists, environmental consultants, monitoring, reporting and verification providers, and potential buyers. Technical partners can help producers develop viable projects and verify results, while buyers provide access to markets for agricultural products and carbon credits.
“Banks need to work with technical and market partners to identify financing needs, address gaps in project preparation and assess whether proposed investments can generate sufficient cash flow,” said Ha.
These partnerships also help determine the type and timing of funding required. Preliminary assessments and emissions baselines may need grants or technical assistance, while equipment, infrastructure, and working capital can be financed through loans once repayment prospects are established. Guarantees may help address specific credit risks, with agreements among funding partners defining how costs and risks are shared rather than leaving farmers and cooperatives to bear the burden.
For Agribank, this approach would involve assessing projects against their technical requirements, commercial viability, and environmental performance. Existing green credit programmes and environmental and social risk management procedures provide a basis for such assessments. Initial lending pilots could cover low-emission rice cultivation, livestock and biogas, forestry, waste treatment, and biomass utilisation, allowing the bank to evaluate financing structures across different agricultural value chains.
However, extending lending to projects reliant on carbon income also depends on the legal status and financial treatment of environmental assets. “Lenders need clarity on ownership, transfer rights and the distribution of proceeds, as well as the treatment of receivables and collateral. Accounting, taxation and foreign exchange requirements also affect how future income can be assessed,” Ha added.
Alongside these legal requirements, monitoring and verification costs can weigh heavily on smaller producers. Shared data systems and group-based approaches, where permitted, could help distribute expenses, although technical support would still be needed. Even where emissions reductions are verified, the resulting credits may not generate immediate income.
“Verified emissions reductions do not necessarily translate into timely payments, as revenue depends on buyer availability, contractual terms and settlement schedules,” Ha explained.
